



Dear Reader,
You have probably seen the full page ads. The ones promising 14%, or even higher, returns on what are fixed income instruments. The numbers and the promises are hard to miss. It has also prompted a reasonable question from investors that if someone is offering 14%, then why is the debt portion in their portfolio paying only 6-7%?
I would like to answer this question, to the best of my ability.
Return is the price of risk and someone is always setting that price
When a company offers 14% on a fixed income product, they are indirectly telling you something. They are saying that a bank with its armies of lawyers, credit teams, analysts, monitoring systems, recovery processes was not willing to lend to them at 8 or 9%. The bank even has thousands of borrowers to spread the risk. So here they are, offering you something that looks irresistible.
Consider how a bank works. It pays depositors like you and I, 6-7% and then lends that money at 9% or higher depending on the borrower and the collateral. Note that the bank takes risk pretty seriously. Risk management is an entire function within the bank with systems built to manage and support it.
When a borrower approaches you directly with a return that’s much higher than what a decent bank is offering, that offer comes without the protections a bank or other professional lender would want in place. So ask yourself what are you being asked to risk for this extra return.
The asymmetry nobody mentions in the advertisement
In wealth there are two very different things that we casually call risk.
There is the risk that an investment falls in value for a while and takes time to recover. That is actually volatility: uncomfortable, but something a long-term portfolio is designed to absorb. Then there is the risk that some of the money is simply gone. Those two risks should not be treated alike.
When we invest in equity, we accept the volatility. After all, we get to participate in the growth of the business which in the course of years can be much higher than any interest it pays. There is no such upside in the case of high-yield debt. The return is capped at the interest promised. The risks, though, remain. In case of a default, the loss is severe and often permanent.
That’s the asymmetry to me. Double digit fixed return shouldn’t be confused for safer equity like growth.
Ratings don’t help as much as you think here. IL&FS and DHFL carried the highest credit rating before their defaults. Ratings are assessments of credit worthiness rather than guarantees. They can change as conditions change, and sometimes after problems are already visible on the horizon.
What asset allocation is actually for
The job of good asset allocation is to match each rupee to the job it is meant to do. Money you will not need for 7 years or more can afford the volatility of equity, because equity needs time to work.
The money you will need in a couple of years has a different job description. It needs to be present when you need it, without fail. Stability is the entire point here. The problem begins when we ask the same money to do both jobs.
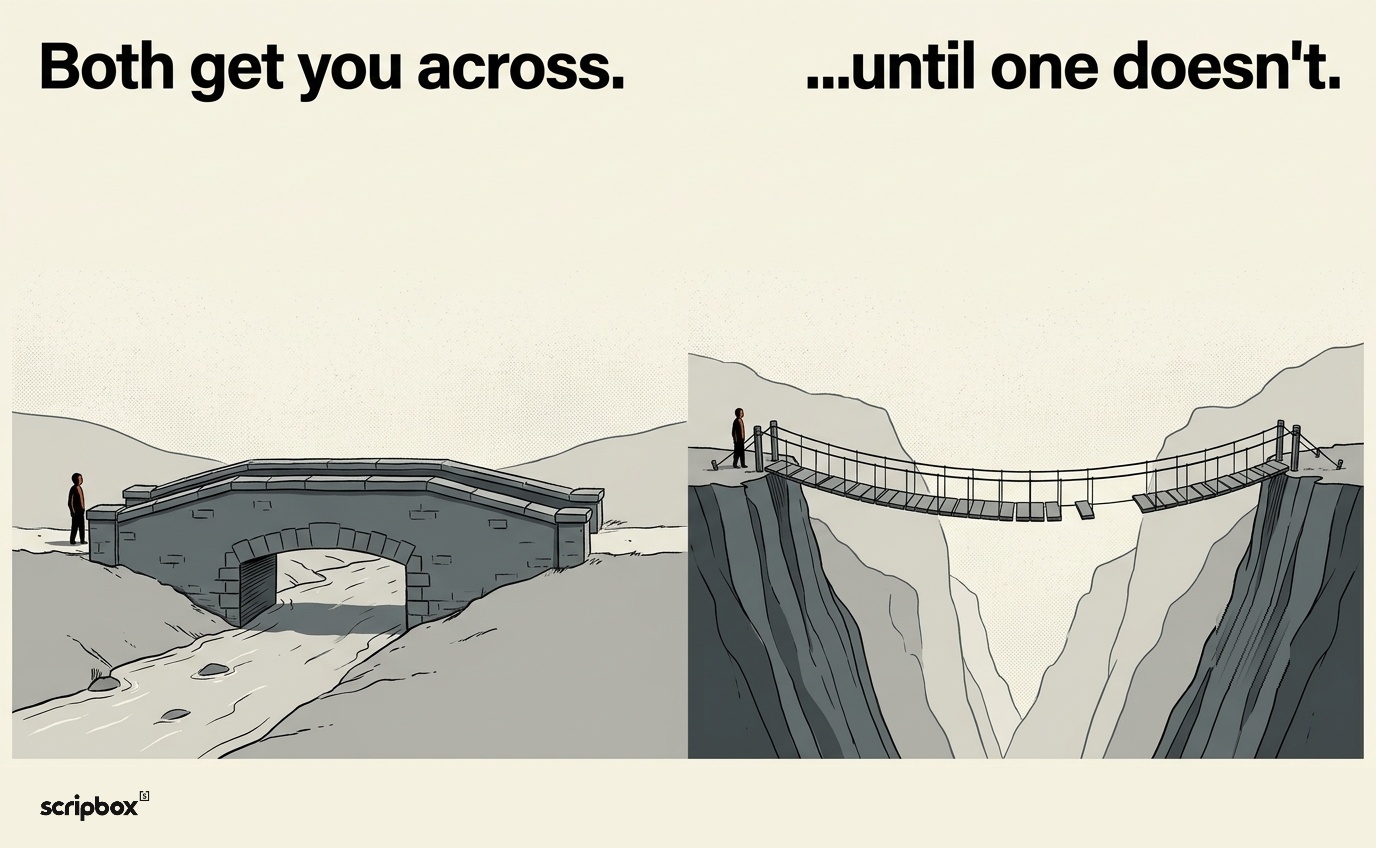
Investments can’t be secure and stable and high growth all at the same time. A double-digit fixed return is a different kind of risk, one with less upside and the same capacity to hurt rather than just a safer version of equity like growth.There is a reason why the debt funds we recommend rarely look exciting returns wise.
The near term portion of your portfolio is there to allow your long term portion to do its actual job of growing your money ahead of inflation and not be sold ahead of time. The boring part of your portfolio is what gives the exciting part time to work. That is not a compromise, rather that is the design.
With warm regards,
Atul Shinghal
CEO and Founder, Scripbox
P.S. If you have a significant financial need coming up in the next two years or so, like a fee or a big purchase, a date already fixed in your head , look at where the money is sitting today. If it’s taking more risk than the goal says it should, it’s worth taking corrective action before markets make the decision for you.


 Google Play
 App Store

Show comments